
- Corn 15 ½ to 11 ¾ higher
- Soybeans 20 ¾ to 24 ½ higher
- Wheat 8 ½ to 12 ½ higher
- Basis Flat/Lower
- Live Cattle 503 higher (220.95)
- Dow Jones 430 higher (52,510)
- Crude Oil 406 lower (92.02)
- Feeder Cattle 675 higher (330.25)
Meetings between high-ranking Chinese and US trade representatives were held over the weekend and with each new positive statement by US Treasury Sec Bessent over the weekend and Monday, the bullish momentum built in all market's hopeful of a much more comprehensive trade deal. Ag products are not going to be the main point of the negotiations, but they were important parts of the early negotiations as the US and China both try to get back on track to the guidelines from the Phase 1 trade deal in 2018. While Chinese news was a main feature of the day's news, it was not the only bullish news as US harvest remains in neutral with heavy rains water logging fields from Nebraska to the east coast. With the official meeting not set to start until Thursday, the trade will be closely watching and listening to the daily updates from the highest level on trade meetings ever on US soil between the US and China.
News and Notes:
- The inconsistent and tough growing season for the WCB continues as most of the region went from extreme heat and drought in July and August to unseasonably wet over the last 10-days. Harvest has stopped from E NE to Ohio and north to the Great Lake States as the rain needs to stop and the ground needs to dry out. The southern tier of the US is expected to see a cooling trend starting mid-week to finally escape the record summer heat.
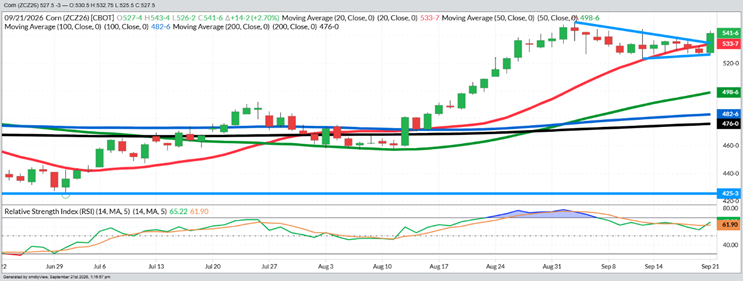
- The daily December corn chart is on Page 2 and shows today’s sharp breakout which confirms a bullish breakout from last week’s tight bull pennant formation and the cooling of the overbought conditions (RSI in the bottom box) that allowed the funds to re-enter long positions they had taken profit on in last week’s modest selloff. The funds are back over 2 BBU in their speculative position, which is large but considering everything that is going on in the corn market, not a surprise. The Sep 2nd contract high of $5.49 ¾ is the only overhead resistance on the daily charts, while the weekly and monthly charts now point to the late 2022 and early 2023 highs from $6.20-$7.00. Today’s close was $5.43.
- Please take a few minutes to listen to the latest podcast we did for Helena’s FieldLink where the latest in agriculture government affairs are discussed and my general overview of the recent USDA report and the road ahead.
- While crop conditions are beginning to lose importance for yield prediction, they were both unchanged from last week with corn at 57% G/E and 58% for beans. The most interesting numbers were the advanced maturity of the crops that was the result of the brutal late summer dry/hot pattern was corn harvest at 13% and 2% above the 5YA while bean harvest was 12% and 4% over the 5YA. Advanced maturity and a fast harvest often indicate a dry end to the growing season and correlate well to less than spectacular yields. With 2-weeks before the next USDA yield update, the industry seems comfortable with a corn yield at 176-177 and bean yield hovering around 53.
- The key negotiation points for the ag markets are a return to the Bussan Trade deal and the $17 billion annual Chinese purchase promise, a new and lower tariff agreement where both sides give a little to potentially get a lot, and some potential new purchases of corn and cattle. As with the 2018 Phase 1 trade deal, enforceability and the willingness of both sides to adhere to the agreement becomes the most important long-term development. Judging by market reaction, the pinch of higher prices and shrinking world stocks and two wars that are hurting both countries, this meeting has a more congenial and productive feel than any other trade talks with China.
- Friday’s cattle on feed report helped add a bullish spark to the cattle markets today as prices shot up $5-$7 on lower than expected on feed numbers and even smaller placement numbers. Although the on-feed number showed year over year improvement, the placement data helped put in a hard floor after sharp weekly losses last week. The cattle markets are trying to form a bottom.
Sometimes you do not have to dig too deep into the news to find the reason for such big market moves. While there are no hard numbers on what China could buy, the fact that they are here, talks are going well and no diplomatic snags have popped up, are reasons enough for the bulls to get excited. While there are ways that the final numbers of the meeting could be disappointing to the bulls, it seems like we have moved past several worst-case scenarios that were present a few weeks ago. Continue to think about affordable call option re-ownership if you are delivering bushels that were sold at lower levels. This could get really exciting this winter.
Sales Targets
Corn
Beans
Wheat
- 2025 Crop Finished Finished Finished
- 100% Sold at $4.48 Avg 100% Sold at $10.67 100% Sold at $6.24 Avg
- 2026 Crop On Hold - Dec ‘26 On Hold – Nov ‘26 On Hold – Sep ‘26
- 70% Sold at $5.10* 70% Sold at $11.61* 85% Sold at $6.45
- Current Price $5.43 $13.28 $7.27
- 2027 Crop On Hold - Dec ‘27 On Hold – Nov ‘27 On Hold – July ‘27
- 10% Sold at $5.20 20% Sold at $11.85 50% Sold at $7.35
- Current Price $5.37 $12.82 $7.48
%’s are total of expected yields. Bold Prices are Updated Sales Targets. * price includes trading
December Corn – Daily
Today’s Market Closes — Rounded to the Nearest Cent
Corn
- December $5.43
- March $5.57
- July $5.65
- September $5.34
Beans
- November $13.28
- January $13.44
- March $13.53
- July $13.61
Wheat
- December $7.27
- March $7.43
- July $7.48
- September $7.51
Other Closes
- Nov Diesel 4.6952 -1492
- Dec Cotton 83.42 +227
- Cash Cattle $225 Offer
- Lean Hogs 78.15 +5
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.