
- Corn 2 ½ to ½ higher
- Soybeans 13 ¾ to 15 higher
- Wheat 5 ¼ to 6 higher
- Basis Flat
- Live Cattle 155 lower (220.70)
- Dow Jones 365 lower (52,078)
- Crude Oil 420 higher (105.59)
- Feeder Cattle 400 lower (333.85)
Sharply higher crude oil and a new record high for diesel futures were the market highlights today as another rebel militant group backed by Iraq bombed the Saudi pipeline that was helping ease the closure of the Straits and Ukraine bombed another Russian refinery. Although the grain and soy markets were lower in early trade, the markets found support from new Chinese demand and more momentum heading into the trade summit. US finishing weather had been a “hot” topic for the last month as the record August heat took yield off the top end potential for both crops, but now the E Nebraska, all of Iowa, southern Minnesota and northern Illinois are facing the flooding rains this week to further deteriorate the crops and complicate harvest as the forecast for most of the Midwest remains wet for the 7-10-day period. One other supportive factor is that the shoulder season September futures contract expired today, which finished remaining deliveries and puts the new crop December corn and November bean futures as the only remaining 2026 contracts to trade.
News and Notes:
- The finish to the Corn Belt growing season looks a lot like the growing season with an extreme of conditions. The WCB has been too hot and too dry for most of the summer but now are receiving too much rain and heading into a wet outlook as early harvest should be rolling. Harvest delays are expected across Iowa and its bordering states due to the forecast. The south will remain freakishly hot with heat indexes well over 100 for at least the next week. The US weather this year has seen the largest monthly swings of position I can remember.
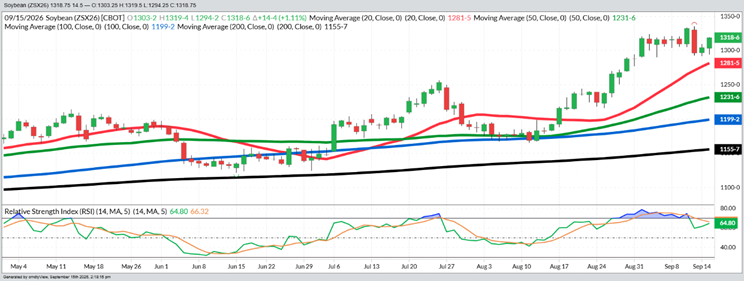
- The November daily bean chart is on page 2 and after a needed 10-day period of consolidation including the new contract highs last Friday, the market found end user and speculative support at today’s lows before an impressive bounce. The funds never trimmed their long position much during that consolidation, but the overbought conditions from late August until the report has gotten better. The interesting thing about the chart is the 10-day plateau traded the $13.05 ¾ price every day during that streak. Much like corn’s recent attachment to $5.36 ½, the trade is finding parity at these higher levels at the best mid-September prices in years.
- Crop ratings were better than expected in Monday’s report with corn unchanged and beans only down 1% from the previous week. With the crops rapid maturity this is not a surprise as this is usually what happens in late September as the crops quit growing.
- Russia and Ukraine and the US and Iraq have a lot in common. None of the four keep their diplomatic pledges very long and if all four countries are determined to push these wars until somebody is forced to surrender, these indeed may have no end in sight. This is bad news for gas and diesel prices as other rebel factions are taking Iraq’s side and bombing more OPEC infrastructure and if Ukraine continues to bomb Russia’s refineries, it will be hard to predict how high diesel and gas prices could go. Prices rise sharply because of market panic and to force the decision makers to change course. It is unclear how high energy prices would need to go to end either war.
- Both cattle markets have been on impressive rallies from the sharp August breaks with live cattle futures rallying over $10 in the last 2-weeks while feeder cattle had rallied over $25 before today’s sharp reversal. World stock market weakness was a contributing factor today, but the markets ran into resistance at the early August highs. EH factors that drove the markets lower (reopening the Mexican border and a President intent on lowering beef prices) are still in play, so further rallies may be difficult. Call us about hedge protection if you are uncovered for your fall/winter deliveries.
There have been enough interesting things to write about this year but as we go to the next chapter of the growing season of US harvest and SA planting, more plot twists are probably in store. CONAB announced their expectation that both Brazil’s planted acreage and total crop will contract from the previous year for the first time ever. High fertilizer prices and concern over Chinese demand switching to the US are parts of the decision. Super El Nino and a SA weather problem that leads to yield loss would make August price action look tame. Stay tuned and think about overhead coverage on bushels you must sell out of the field.
Sales Targets
Corn
Beans
Wheat
- 2025 Crop Finished Finished Finished
- 100% Sold at $4.48 Avg 100% Sold at $10.67 100% Sold at $6.24 Avg
- 2026 Crop On Hold - Dec ‘26 On Hold – Nov ‘26 On Hold – Sep ‘26
- 70% Sold at $5.10* 70% Sold at $11.61* 85% Sold at $6.45
- Current Price $5.36 $13.19 $7.29
- 2027 Crop On Hold - Dec ‘27 On Hold – Nov ‘27 On Hold – July ‘27
- 10% Sold at $5.20 20% Sold at $11.85 50% Sold at $7.35
- Current Price $5.36 $12.75 $7.51
%’s are total of expected yields. Bold Prices are Updated Sales Targets. * price includes trading
November Beans – Daily
Today’s Market Closes — Rounded to the Nearest Cent
Corn
- December $5.36
- March $5.50
- July $5.60
- September $5.33
Beans
- November $13.19
- January $13.35
- March $13.43
- July $13.53
Wheat
- December $7.29
- March $7.45
- July $7.51
- September $7.54
Other Closes
- Oct Diesel 5.2564 +2949
- Dec Cotton 84.48 -7
- Cash Cattle $224 Offer
- Lean Hogs 79.08 -53
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
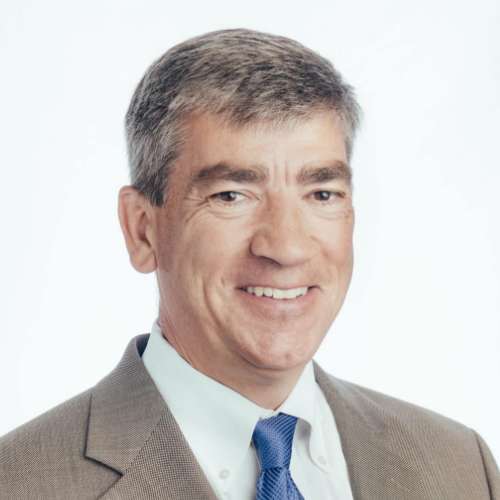
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
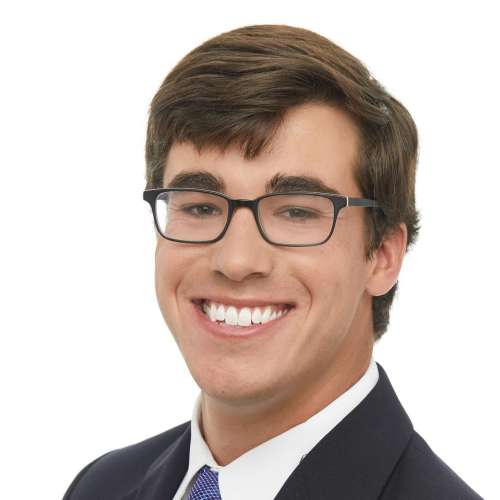
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.