
- Corn 1 ½ to 2 ¼ lower
- Soybeans 1 ¾ to 3 ½ higher
- Wheat 1 ½ to 2 ½ higher
- Basis Flat
- Live Cattle 225 lower (218.45)
- Dow Jones 205 lower (51,913)
- Crude Oil 308 lower (102.74)
- Feeder Cattle 420 lower (329.65)
The slowest news day in a few weeks saw markets chop in modest ranges with crude oil falling over $3 a barrel while the world markets waited for today’s US Federal Reserve rate decision. The lack of news allowed for prices to retreat slightly, but technical trends have not been damaged and have even improved slightly, as the markets consolidate around comfortable price levels ahead of the US/China trade summit and additional harvested yield data. Quiet but sitting on a spring is a good way to describe the current market set up.
News and Notes:
- The US weather patterns remain consistent with heavy rain from E NE to the Great Lake states for the next 5-7-days while the southern tier of the US remains under unrelenting heat. Rain totals will figure heavily into Sunday night’s opening as the stressed corn crop may not be able to stand up to much wind or excessive moisture.
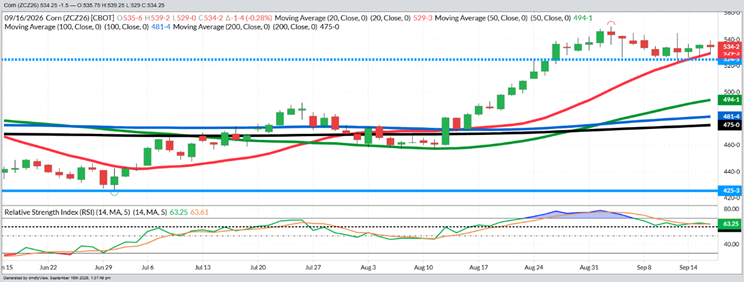
- The December daily corn chart is on Page 2 and shows continued consolidation today, but the daily trade has respected the old breakout price of $5.24 ½ (blue dotted line) and the 20-DMA (red line) for the last 6 trading sessions. All 6 of those sessions have traded the $5.30 ¾ to $5.34 ¾ range which should continue to act as a comfortable plateau until the market has a good reason to make another run at the Sep 2nd contract high at $5.49 ¾. That reason could be China announcing a new corn purchase program next week or another port strike in the Black Sea. Another important factor is that the RSI (Relative Strength Index), which is the bottom box on the chart which indicates overbought or oversold conditions, is the most neutral (63.25) since Aug 18th when the market accelerated the breakout and then added another 62-cents in the next 2-weeks. I’m not expecting that type of short-term run, but it does show the funds are in a spot to add to their net long in a calmer environment than at the Sep 1st high went it went to 79.04, the day before the current contract high was made.
- The Federal Reserve hiked interest rates by 1/4 point for the first time since 2020 to address stubborn inflation that has been driven mostly by record high diesel prices and multi-year high gas prices. A rate hike will not lower energy prices, a hike will only add additional interest expense to an already angry US households. I would not want to be an incumbent Republican running for re-election.
- There have been no meaningful “facts” updated about diplomatic progress in either war. Each countries respective leader talks about ceasefires and peace, but the actions of their militaries are the opposite. With the Red Sea oil export capacity diminished by the Houthi rebels, and the Houthis bombing of the Saudi pipeline, the world will not see an to end to high gas prices anytime soon.
- While it has not been talked about much with the trade summit coming up first, the USDA/WASDE quarterly stocks report on Sep 30th will offer more data on demand and tightening domestic stocks. The October USDA report should have several interesting wrinkles if they update China’s purchase pledges after the meeting and further cut corn yields as the trade expects.
- Fresh export news was absent today, but chatter continues to be heard that both China and the US are moving to lower existing tariffs on each other ahead of the meeting. Ethanol production was unchanged from last week with extremely profitable margins. With record high diesel prices and the US oil reserves at 42-year lows, the bio-fuel profit margins will stay strong for months.
Consolidation and back and forth choppy trade are good for the long-term health of bull markets, and the grain and soy markets are currently in the middle of that pattern. The long list of bullish factors is unchanged and believing that no news is good news about the US/China trade summit will make the initial comments and outcome of next weeks meeting the next important milestone. If the markets consolidate for another week and get good news from the trade meeting, the bull markets have plenty of reason to retest each of the contract highs. Guarded optimism is developing with each passing day where no reverse Black Swan event kills the bulls enthusiasm. Please contact us if you are selling bushels off the combine with no upside risk protection, so we can explain the pros and cons of trading futures and options to address that risk.
Sales Targets
Corn
Beans
Wheat
- 2025 Crop Finished Finished Finished
- 100% Sold at $4.48 Avg 100% Sold at $10.67 100% Sold at $6.24 Avg
- 2026 Crop On Hold - Dec ‘26 On Hold – Nov ‘26 On Hold – Sep ‘26
- 70% Sold at $5.10* 70% Sold at $11.61* 85% Sold at $6.45
- Current Price $5.34 $13.21 $7.31
- 2027 Crop On Hold - Dec ‘27 On Hold – Nov ‘27 On Hold – July ‘27
- 10% Sold at $5.20 20% Sold at $11.85 50% Sold at $7.35
- Current Price $5.34 $12.77 $7.52
%’s are total of expected yields. Bold Prices are Updated Sales Targets. * price includes trading
December Corn – Daily
Today’s Market Closes — Rounded to the Nearest Cent
Corn
- December $5.34
- March $5.49
- July $5.58
- September $5.30
Beans
- November $13.21
- January $13.37
- March $13.45
- July $13.55
Wheat
- December $7.31
- March $7.47
- July $7.52
- September $7.57
Other Closes
- Oct Diesel 5.2514 -106
- Dec Cotton 84.36 -12
- Cash Cattle $224 Offer
- Lean Hogs 78.68 -40
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.