
- Corn 2 ¼ to 3 ½ higher
- Soybeans 7 ¾ to 9 ½ higher
- Wheat 3 ¼ to ½ lower
- Basis Flat
- Live Cattle 258 higher (222.25)
- Dow Jones 145 lower (52,440)
- Crude Oil 134 higher (101.39)
- Feeder Cattle 535 higher (337.85)
The new week started with a less volatile, choppy two-sided day of trade as world traders reacted to Friday’s USDA report and tightening world stocks in corn and beans. Corn and beans bounced modestly while wheat was lower on a Russian/Ukraine pledge to stop bombing energy and port infrastructure. Other news was limited which kept volume on the modest side, but an excessively wet forecast for Iowa did bring in another layer of concern that harvest problems could develop from the flooding rains. With confirmation that domestic and world demand continues at a record pace, and the US crops are not going to get any bigger, the trade has to now work out how to motivate additional world planted acres and slow demand. The normal way to accomplish both is for higher prices. This afternoon’s US crop conditions are expected to fall 1-2% again to confirm USDA yields.
News and Notes:
- After all the late season dryness and the poor end to the season, heavy, flooding rain is expected for all of Iowa and parts of their border states. The growing season has been very inconsistent, and this will not help the only state that both good crop ratings and trend line potential. Excessive heat will continue from Texas/Oklahoma through the Delta with no meaningful rain in the forecast.
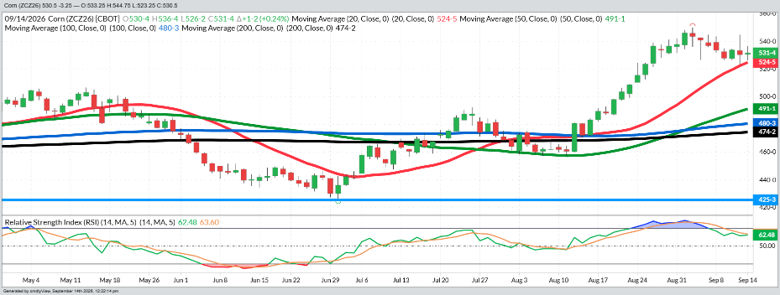
- The December daily corn chart is on Page 2 and shows the volatile report day trade last Friday and the test of the 20-DMA (red line) at $5.24 3/4 both Friday and today. The funds are still holding a massive, long position, but other than the occasional bout of profit taking, the funds still have their bullish factors in place to remain in the trade for as long as they can. A choppy trade is likely to develop between the 20-DMA and the Sep 2nd contract high of $5.49 ¾ into the trade meeting with China.
- There were no daily export sales announcements, but the weekly shipping pace remains consistent for the current record sales totals. Ethanol and bio-diesel margins remain strong and show no signs of contracting. No news is good news leading into the China trade meeting, as everything continues to be on track. Daily Chinese purchases should continue into the meeting.
- Russia and Ukraine apparently have agreed to stop attacks on energy infrastructure. The news sent diesel futures lower after an early rally toward $5. The record diesel prices have been largely due to Russia’s loss of about 50% of their diesel refining capacity because of the war. Russia is the world’s largest refiner and exporter of diesel, so this would at least stabilize the market. Unfortunately, it will take years to bring that refining capacity back online. Diesel prices should stabilize, but I do not think will take prices back to normal levels.
- Of all the numbers that were adjusted in Friday’s report, the one that caught my eye was the corn stocks to use ratio. The ratio fell from 10.12% to 9.68% on the yield cut. A sub 10% stocks to use ratio equates to corn prices above $5.50, with $6 not out of the question if the yield falls further in the October USDA update. For beans, the stocks to use ratio fell below 7% (6.78%) for the first time in over 3-years. The global balance sheets are tightening on both yield loss and exceptional demand.
With the USDA staying consistent on several announced report upgrades, they seem to be slowly regaining the markets trust. With their consistent planted acreage numbers from August to September and their yield estimates easily in line with private estimates, history has shown that once the USDA begins cutting yield (especially corn) the updates in subsequent reports tend to go lower as well. Many analysts think corn yield is in the 176-177 range, which would not make for huge adjustments by the USDA, but if realized it would take another 150-180 MBU off US ending stocks and further tighten the stocks to use ratio. Market consolidation with a bias to the upside remains our outlook. Sell rallies as needed to take some harvest straight to town but look at the solid storage carry in the market as helpful for year end tax and pre-pay planning.
Sales Targets
Corn
Beans
Wheat
- 2025 Crop Finished Finished Finished
- 100% Sold at $4.48 Avg 100% Sold at $10.67 100% Sold at $6.24 Avg
- 2026 Crop On Hold - Dec ‘26 On Hold – Nov ‘26 On Hold – Sep ‘26
- 70% Sold at $5.10* 70% Sold at $11.61* 85% Sold at $6.45
- Current Price $5.33 $13.04 $7.07
- 2027 Crop On Hold - Dec ‘27 On Hold – Nov ‘27 On Hold – July ‘27
- 10% Sold at $5.20 20% Sold at $11.85 50% Sold at $7.35
- Current Price $5.35 $12.64 $7.45
%’s are total of expected yields. Bold Prices are Updated Sales Targets. * price includes trading
December Corn – Daily
Today’s Market Closes — Rounded to the Nearest Cent
Corn
- December $5.33
- March $5.48
- July $5.59
- September $5.32
Beans
- November $13.04
- January $13.20
- March $13.28
- July $13.38
Wheat
- December $7.22
- March $7.39
- July $7.45
- September $7.48
Other Closes
- Oct Diesel 4.9615 +22
- Dec Cotton 84.55 -151
- Cash Cattle $221 Trade
- Lean Hogs 89.60 -193
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.