
- Corn 4 ¾ to 5 ¾ lower
- Soybeans 2 to 3 lower
- Wheat 6 ¼ to 9 ½ lower
- Basis Flat
- Live Cattle 218 lower (218.78)
- Dow Jones 194 lower (52,281)
- Crude Oil 205 lower (90.30)
- Feeder Cattle 223 lower (328.03)
Welcome to the fall of 2026! The last day of summer saw explosive rallies while fall came in more subdued with a choppy two-sided trade with lower closes. Limited trading session news came out of the ongoing US/China trade meetings as President Trump made his yearly address to the United Nations. Unchanged weekly crop conditions added modest pressure to prices, but opportunistic farmer selling off the combine has been a big part of any selling this week. All market participants will be closely following any additional news from Washington to hopefully fulfill the bullish expectations from the trade meeting and potentially expanding on the Phase 1 trade deal.
News and Notes:
- Drier and more seasonal temperatures are expected to help dry out the wettest parts of the Corn Belt and restart harvest in many areas this week. With the early maturity of this years US crop, there is no concern of a belt wide freeze before full crop maturity. SA weather now takes the forefront of all-weather news as N Brazil remains dry with the early withdrawal of their winter monsoon. Super El Nino is living up to expectations, with a dry pattern for N Brazil but excessively wet for S Brazil and N Argentina. While Brazil’s planting is in its very early stages, their weather patterns are a concern.
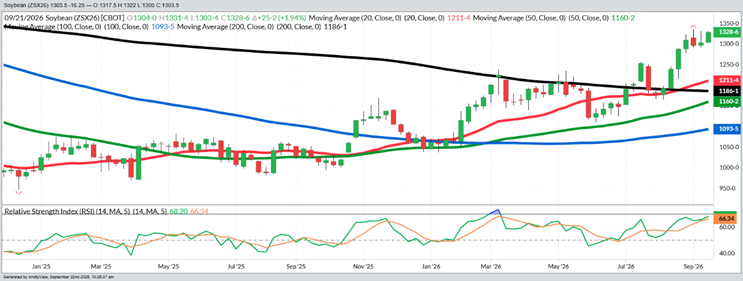
- The weekly front month bean chart is on Page 2 and shows the comfortable plateau that the month of September has been sitting on from $12.92 to $13.35. With Monday’s sharp rally to within 3-cents of the contract and 2 ½ year high, the chart is showing the same potential bullish pennant formation that we saw in corn recently. A weekly close over $13.35 brings in $14 as the next overhead technical target, which is also the 34-month high. The funds are long 1.2 BBU and now hold their largest net long position in the last month, despite the fact that the RSI corrected the overbought condition over the last 3-weeks. The speculative long position does not tell the whole picture as it is highly probable China was the largest buyer of futures over the last 2-weeks to cover upcoming purchases when farmers were selling early harvest and the funds were taking profits. If China has already hedged their cash purchases, the funds will have to offset farmer selling to keep the market rallying.
- The development of this year’s super El Nino was accurately forecast and with warming Pacific waters, the patters were as expected in late summer. The most glaring thing that jumps out from a “typical” strong or super El Nino pattern is reduced Atlantic/Gulf hurricane formation. For the first time on record, there have been ZERO named hurricanes in either body of water. That is extreme and should act as a cautionary tale of what the southern hemisphere weather pattern could be if they see that extreme impact. There should be several SA weather concerns this year in a growing season that needs to be near perfect to add to the tight world stocks picture.
- The world energy markets got a 3-hour off agenda meeting between the US and Iran at the UN meeting. The meeting was called “productive”. There were no new developments between Ukraine and Russia. The wars may end someday, but it does not look like it will happen anytime soon.
- The headline driven trading systems are ready to see any news on what the US and China agree on tariffs and if they set a maximum 20% tariff cap and eliminate the 10% duty on private Chinese bean purchases. If both of those are agreed to, expect more rallies. With US corn yield falling the domestic stocks to use ratio falling under 10%, even a modest 150-200 MBU of new corn purchases by China would start a serious demand rationing rally to keep the rest of the world from panic buying other world supplies. The final trade deal details decides if corn goes to $6 and beans to $14.
While the trade voted with optimism during Monday’s sharp rallies, everyone must wait to hear the announcements of everything before accelerating or pausing the rally. Never say never, but it appears the worst-case scenario of no meaningful improvements in trade with China are off the board. It is now about dissecting the details to determine what fair value is for each market when they are announced. With meetings expected through Friday afternoon, it would be consistent with this administration to not announce the details until this weekend. Stay tuned.
Sales Targets
Corn
Beans
Wheat
- 2025 Crop Finished Finished Finished
- 100% Sold at $4.48 Avg 100% Sold at $10.67 100% Sold at $6.24 Avg
- 2026 Crop On Hold - Dec ‘26 On Hold – Nov ‘26 On Hold – Sep ‘26
- 70% Sold at $5.10* 70% Sold at $11.61* 85% Sold at $6.45
- Current Price $5.37 $13.26 $7.17
- 2027 Crop On Hold - Dec ‘27 On Hold – Nov ‘27 On Hold – July ‘27
- 10% Sold at $5.20 20% Sold at $11.85 50% Sold at $7.35
- Current Price $5.32 $12.82 $7.40
%’s are total of expected yields. Bold Prices are Updated Sales Targets. * price includes trading
November Beans – Weekly
Today’s Market Closes — Rounded to the Nearest Cent
Corn
- December $5.37
- March $5.51
- July $5.60
- September $5.29
Beans
- November $13.26
- January $13.41
- March $13.49
- July $13.59
Wheat
- December $7.17
- March $7.33
- July $7.40
- September $7.45
Other Closes
- Nov Diesel 4.7675 +535
- Dec Cotton 82.87 -55
- Cash Cattle $225 Offer
- Lean Hogs 79.28 +113
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.