
- Corn ½ to 1 higher
- Soybeans ½ to 1 ½ higher
- Wheat 3 ¼ to 3 ¾ lower
- Basis Flat
- Live Cattle 20 lower (218.88)
- Dow Jones 446 higher (52,163)
- Crude Oil 220 lower (92.41)
- Feeder Cattle 318 higher (334.93)
The end of week trade tested the nerve of both the bulls and bears as disappointment with a lack of fresh news from the US/China trade meetings and technically based selling led to sharp morning breaks and fear that the trade meetings had been a failure for ag. But, after the early losses in all three markets, end users and speculative buying emerged to recapture all of the double-digit losses and push corn and beans into positive closes while wheat finished with modest losses. Reports of world political pressure to reopen the Black Sea humanitarian shipping corridor and “meaningful” talks between the US and Iran ramped up Friday’s volatility as diesel fell to its lowest price in 3-weeks. Headlines, massive egos, and enormous speculative investment will continue to whipsaw our markets for the foreseeable future.
News and Notes:
- The super El Nino pattern is already affecting the southern hemisphere s Australia’s rainy season has ended early with an extended period of drier weather forecast through their wheat pollination. SA is also seeing similar disruptions, and both patterns are consistent with the super El Nino pattern in the past. Market weather scares during the SA growing season seem inevitable. US weather remains wet for the WCB harvest with the central and eastern portion of the Midwest seeing a few drier pockets for harvest progress.
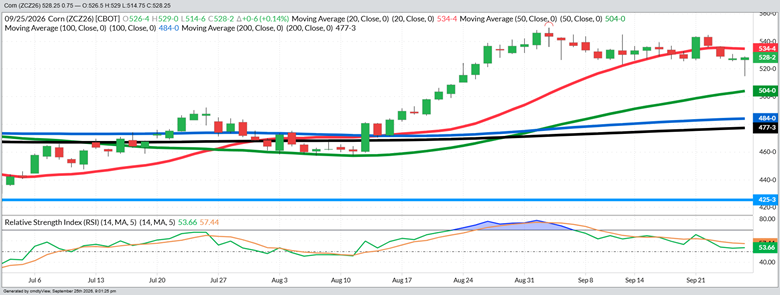
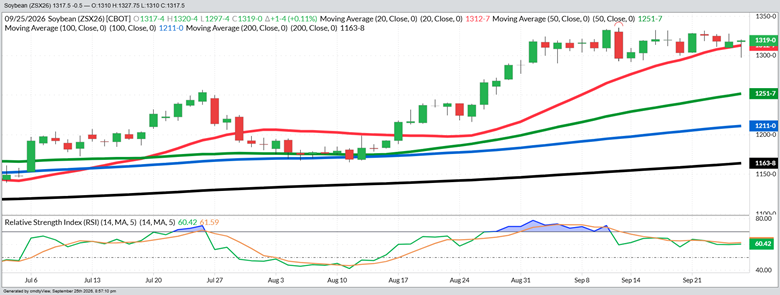
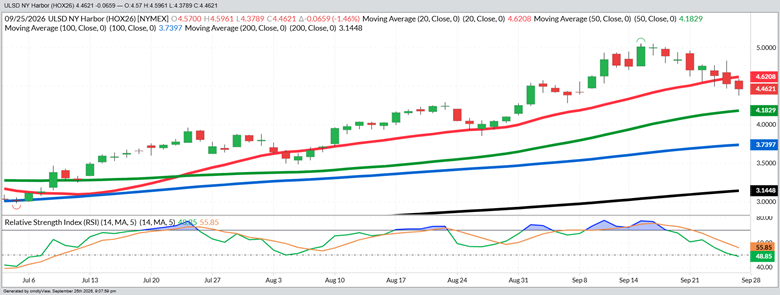
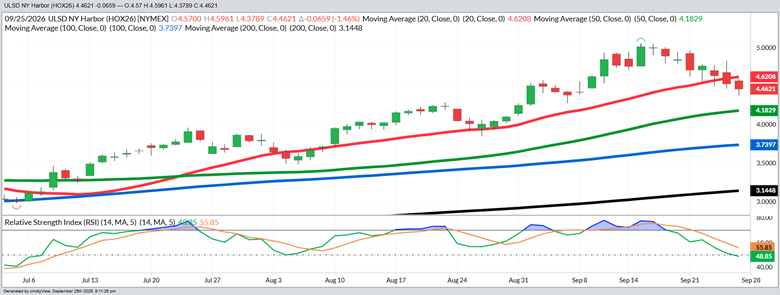
- The common denominator in the corn, bean and wheat charts on Page 2 is the spike formation in Friday’s trade. The funds did their best to wash out the weak longs on today’s sharp break lower as the volume was not large enough to indicate a comprehensive panic sellout from all traders currently long. Once the suckers were cleared out and both end users and speculators realized that this administration loves the flair for dramatic weekend announcements, the rebound and heavier volume buying started. The bean chart looks like an upside breakout is forming, while the corn and wheat charts have seen some technical damage on the daily charts, but did not do any damage to the weekly and monthly charts. The diesel chart looks great if you like cheaper diesel prices as the ongoing break has dropped prices over 60-cents a gallon in the futures in the last 2-weeks. A potential ban on US exports and negotiations with Iran to re-open the Straits have been a big help.
- This week’s trade meeting has made it difficult to look toward the horizon and upcoming news, but Wednesday’s Quarterly Grain Stocks Report will both end the month and give the trade a much sharper look at what the markets are dealing with heading into the fall and winter. The strong margins in ethanol and bean crush are expected to show up in increased use and smaller stocks. It also may help explain why there remains normal carry in the markets despite the bullish trend and falling US corn yields. The next yield update will be the Oct USDA report on Friday the 9th.
- Weekly Changes: Corn + 1 (Dec ‘26), + 15 1/2 (Nov ‘26), Wheat - 11 (Dec ’26), Crude - 781, Diesel - 5857, Dow +402, US Dollar +1080, Cattle +295, Feeder Cattle+1143 , Hogs+12, Cotton +156, Milk -53 (15.16).
All of the above content was written Friday night while this paragraph was written on Sunday after waiting for official announcements of what happened and was agreed upon at the US/China trade Summit. Consistency of message and inconsistency of policy with this administration has kept all of us on their toes but the weekend news was supportive as China made an official positive statement about the meetings (which they did not after the previous two meetings) and both sides have agreed to drop the bi-lateral tariffs on everything mentioned in the $30 billion trade agreement which includes all the agricultural products. Another $17 billion in ag products (mainly corn and wheat) was not officially mentioned but was one large piece of the ag negotiations that the US pushed for. The bullish trade optimism from last Sunday night should return tonight with opening calls 5-8 higher for corn, beans, and wheat. Another weekend development was Ukraine launched their largest one-day attack on Russian infrastructure firing over 1400 drone missiles to further compromise Black Sea shipping capacity and emphasize that neither side is in a conciliatory mood to settle the war. President Trump also rejected Iran’s proposal to re-open the Straits as China and the US agreed in the meeting that Iran should not have nuclear capabilities. Have a great Sunday and please be safe in the field.
December Corn – Daily
November Beans – Daily
December Wheat - Daily
October Diesel – Daily
Sales Targets
Corn
Beans
Wheat
- 2025 Crop Finished Finished Finished
- 100% Sold at $4.48 Avg 100% Sold at $10.67 100% Sold at $6.24 Avg
- 2026 Crop On Hold - Dec ‘26 On Hold – Nov ‘26 On Hold – Sep ‘26
- 70% Sold at $5.10* 70% Sold at $11.61* 85% Sold at $6.45
- Current Price $5.28 $13.19 $7.03
- 2027 Crop On Hold - Dec ‘27 On Hold – Nov ‘27 On Hold – July ‘27
- 10% Sold at $5.20 20% Sold at $11.85 50% Sold at $7.35
- Current Price $5.28 $12.77 $7.26
%’s are total of expected yields. Bold Prices are Updated Sales Targets. * price includes trading
Previous Sales Levels
Corn
Beans
Wheat
-
2025 Sales Sales
Dec ’25 $4.45 (25% on 11-7-24)
Dec ’25 $4.42 (25% on 12-11-24)
Mar ’26 $4.50 (10% on 10-28-25)
Mar ’26 $4.50 (10% on 12-12-25)
Mar ’26 $4.35 (10% on 2-5-26)
May ’26 $4.55 (10% on 3-6-26)
July ’26 $4.75 (10% on 5-1-26)Nov ’25 $10.60 (25% on 9-3-24)
Nov ’25 $10.90 (25% on 9-24-24)
Nov ’25 $10.25 (15% on 1-2-25)
Nov ’25 $10.55 (10% on 8-22-25)
Nov ’25 $10.52 (15% on 10-27-25)
Mar ’26 $11.05 (10% on 10-28-25)July ’25 $7.50 (20% on 5-22-24)
July ’25 $6.35 (25% on 10-1-24)
July ’25 $5.95 (15% on 2-3-25)
Sep ’25 $5.90 (20% on 6-20-25)
Dec ’25 $5.40 (20% on 7-3-25) -
2026 Sales Sales
Dec ’26 $4.75 (10% on 6-20-25)
Dec ’26 $4.70 (10% on 11-14-25)
Dec ’26 $4.70 (10% on 12-2-25)
Dec ‘26 $4.65 (10% on 2-24-26)
Dec ’26 $4.85 (10% on 3-9-26)
Dec ’26 $5.05 (10% on 5-5-26)
Dec ‘26 $4,82 (10% on 7-22-26)Nov ’26 $10.75 (15% on 8 21-25)
Nov ’26 $10.95 (10% on 10-27-25)
Nov ’26 $11.30 (10% on 12-2-25)
Nov ’26 $10.90 (10% on 1-28-26)
Nov ’26 $11.90 (5% on 5-4-26)
Nov ’26 $12.25 (10% on 7-23-26)
Nov ’26 $12.75 (10% on 7-28-26)July ’26 $6.45 (25% on 6-20-25)
July ’26 $5.80 (25% on 11-4-25)
July ’26 $6.60 (15% on 5-12-26)
Sep ’27 $7.15 (20% on 8-26-26) -
Current ’26 Trading Profits Sales
31-cents per bushel
15-cents per bushel
No Positions Recommended
-
2027 Sales Sales
Dec ’27 $5.20 (10% on 7 25-26)
Nov ’27 $11.50 (10% on 5-4-26)
Nov ’27 $12.15 (10% on 8-26-26)July ’27 $7.15 (25% on 5-12-26)
July ’27 $7.55 (25% on 8-26-26)
Today’s Market Closes — Rounded to the Nearest Cent
Corn
- December $5.28
- March $5.42
- July $5.52
- September $5.24
Beans
- November $13.19
- January $13.33
- March $13.40
- July $13.51
Wheat
- December $7.03
- March $7.18
- July $7.26
- September $7.31
Other Closes
- Nov Diesel 4.4621 -659
- Dec Cotton 82.71 -60
- Cash Cattle $222 Trade
- Lean Hogs 78.23 -98
A Complete Overview of Current New Crop Market Conditions
Last Updated: 09/27/2026
Fundamentally
Technically
Short Term
Long Term
Volatility
Trade Rec
- Corn Neut/Bullish Neut/Bullish Neut/Bullish Neut/Bullish High None
- Soybeans Neut/Bullish Neut/Bullish Neut/Bullish Neut/Bullish High None
- Wheat Neutral Neut/Bearish Neut/Bearish Neut/Bullish High None
- Cattle Neut/Bearish Neut/Bullish Neut/Bearish Neut/Bullish High None
- Hogs Neut/Bearish Bearish Neut/Bearish Neutral Medium None
- Diesel Neut/Bullish Bullish Neut/Bullish Neutral High None
- Denotes positive change
- Denotes negative change
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.