
- Corn 8 to 4 lower
- Soybeans 8 to 1 ½ lower
- Wheat 8 to 10 ½ lower
- Basis Flat/Higher
- Live Cattle 205 higher (220.83)
- Dow Jones 333 lower (51,950)
- Crude Oil 151 higher (92.05)
- Feeder Cattle 528 higher (3330.30)
A lack of official releases or announcements from the ongoing US/China trade talks weighed on prices for the second straight day with prices falling back and having erased almost all of Monday’s sharp knee-jerk reaction gains. Nothing has materially changed about the size of the US crops, potential trade news from the meetings and record demand over the last two days, but the nervousness driven by President Trump’s meetings and speech at the UN have been reflected in the inability of the markets to find additional buyers after Monday’s move. The timing of the official trade announcements will decide if the week finishes on a strong note or a continued apprehensive note.
News and Notes:
- The next week will continue to be a challenge for thew WCB as rains look to persist into early October while the ECB will see a drier pattern with harvest starting in earnest. The delayed harvest is a bullish aspect of support, but it does not compare to what could happen if the US and China agree on some of the ag trade numbers that were rumored last weekend.
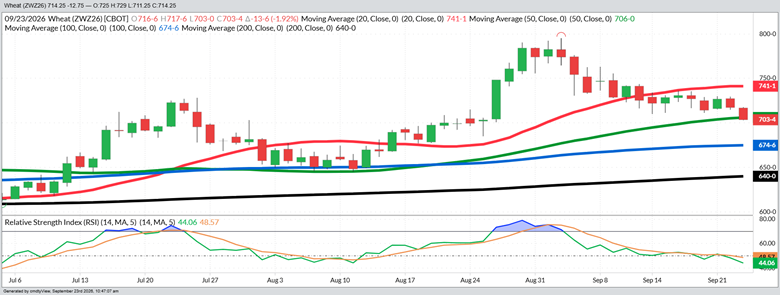
- All three new crop corn and bean contracts fell to or below important technical and psychological support in today’s set back with Dec corn falling back under the 20-DMA, Nov beans testing the 20-DMA and Dec ’26 wheat falling back to the 50-DMA just above $7. The Dec wheat chart is on Page 2 and shows these developments but also shows the September 89-cent pullback since the Sep 2nd contract high at $7.95. This highlights the late August rally when bombs were destroying Black Sea infrastructure and then the fear/hope for a cease fire and/or the re-opening of the humanitarian grain corridor. The stakes are extremely high for world prices if the trapped corn and wheat bushels make it back into the world market and caution was exhibited. If wheat falls another 50-60 cents it would negatively impact corn for at least one-third of the loss. It sounds inhumane to say, but peace breaking out in the Black Sea and the Straits of Hormuz would be very bearish factor for all prices.
- November diesel futures fell to their lowest price ($4.49) in 2-weeks and at today’s lows traded roughly 56-cents below last week’s all-time high of $5.05. These types of quick breaks may not show up in the price offerings from your local supplier, but they are important to watch and help you start a conversation with your supplier to set a price target to top off your tanks. Keeping in touch with all of your suppliers in this crazy environment is the best way to stay on top of things and strengthen the relationships. Diesel’s weakness is being driven by Trump considering stopping US diesel exports. Harder to implement than just saying it will happen. Expect considerable volatility to continue.
- After a day of consolidation on Tuesday, cattle prices were sharply higher again to add to Monday’s big gains. Fedder cattle futures have rallied $12 this week while live cattle futures are only up $5. No cash trade has been set for the week, but rising retail prices and the bullish Cattle on Feed report are adding support to a market that needs fundamental factors and not government factors to find fair value.
- The political headlines from meetings and speeches at the annual UN meeting have surprisingly overshadowed the enormous potential of an expanded US/China trade deal could do to the US balance sheet. The most bullish outcome from the trade meeting is a series of agreements that have been rumored this week. If both sides drop or permanently reduce current tariff levels, China buys even a nominal amount of US corn, and a board of trade concept is approved which would provide a new enforcement layer to US/China trade. Being held accountable has always been a problem.
Rumors start and end rallies, but hard facts are needed to start long-term bullish or bearish trends. This week it has all been about rumors and rhetoric and knee-jerk headline related trading rather than hard facts or meaningful progress toward ending either war. Putin just won re-election which means he has no reason to want the war to stop, and Ukraine did got gain any meaningful world backing to cause Putin any fear. The odds are the Black Sea shipping impasse does not end soon. Iran has no reason to concede anything to Trump before the US mid-term elections next month. Not listening to the noise is impossible and requires discipline but staying the course is a necessity in your marketing plan is a must.
Sales Targets
Corn
Beans
Wheat
- 2025 Crop Finished Finished Finished
- 100% Sold at $4.48 Avg 100% Sold at $10.67 100% Sold at $6.24 Avg
- 2026 Crop On Hold - Dec ‘26 On Hold – Nov ‘26 On Hold – Sep ‘26
- 70% Sold at $5.10* 70% Sold at $11.61* 85% Sold at $6.45
- Current Price $5.29 $13.18 $7.07
- 2027 Crop On Hold - Dec ‘27 On Hold – Nov ‘27 On Hold – July ‘27
- 10% Sold at $5.20 20% Sold at $11.85 50% Sold at $7.35
- Current Price $5.28 $12.81 $7.32
%’s are total of expected yields. Bold Prices are Updated Sales Targets. * price includes trading
December Wheat - Daily
Today’s Market Closes — Rounded to the Nearest Cent
Corn
- December $5.29
- March $5.43
- July $5.53
- September $5.28
Beans
- November $13.18
- January $13.33
- March $13.42
- July $13.54
Wheat
- December $7.07
- March $7.23
- July $7.32
- September $7.40
Other Closes
- Nov Diesel 4.6400 -1218
- Dec Cotton 82.95 +8
- Cash Cattle $225 Offer
- Lean Hogs 79.88 +60
Any decision to purchase or sell as a result of the opinions expressed in this report will be the full responsibility of the person authorizing such transaction. No market data or other information is warranted by Reliance Capital Markets II LLC as to completeness or accuracy, express or implied, and is subject to change without notice. Any comments or statements made herein do not necessarily reflect those of Reliance Capital Markets II LLC, or their respective subsidiaries, affiliates, officers or employees. Disclaimer: Past performance is not indicative of future results. Strategic Trading Advisors is a registered DBA of Reliance Capital Markets ll LLC.
About Jody Lawrence
Jody Lawrence has been in the commodity brokerage and agriculture marketing business since 1992 and started Strategic Trading Advisors in 1999 and runs it today with his son Brady. The daily market comment his company publishes has over 7000 subscribers in 33 states and 3 countries and provides a concise overview of the world markets with ideas on farm hedging and marketing. Jody also travels the country giving 60-70 marketing meetings a year through his 22-year strategic partnership with Helena Agri-Enterprises.
About Brady Lawrence
Brady Lawrence is an Agriculture Market Specialist and Financial Advisor that focuses on commodities markets, futures and options brokerage, and helping individuals and families plan for retirement and their financial futures. Brady joined Jody at Strategic Trading Advisors in 2018 after college and supports the market research and brokerage sides of the business.